Powered by Obi Mbieri Independent Media Ltd · eziokwubundu.com
How to get microfinance loan in southeast Nigeria
Access to affordable credit remains one of the most significant barriers facing small business owners, farmers, and traders across southeast Nigeria. Whether you operate a provisions stall in Onitsha, run a poultry farm on the outskirts of Enugu, or manage a tailoring workshop in Owerri, understandi...
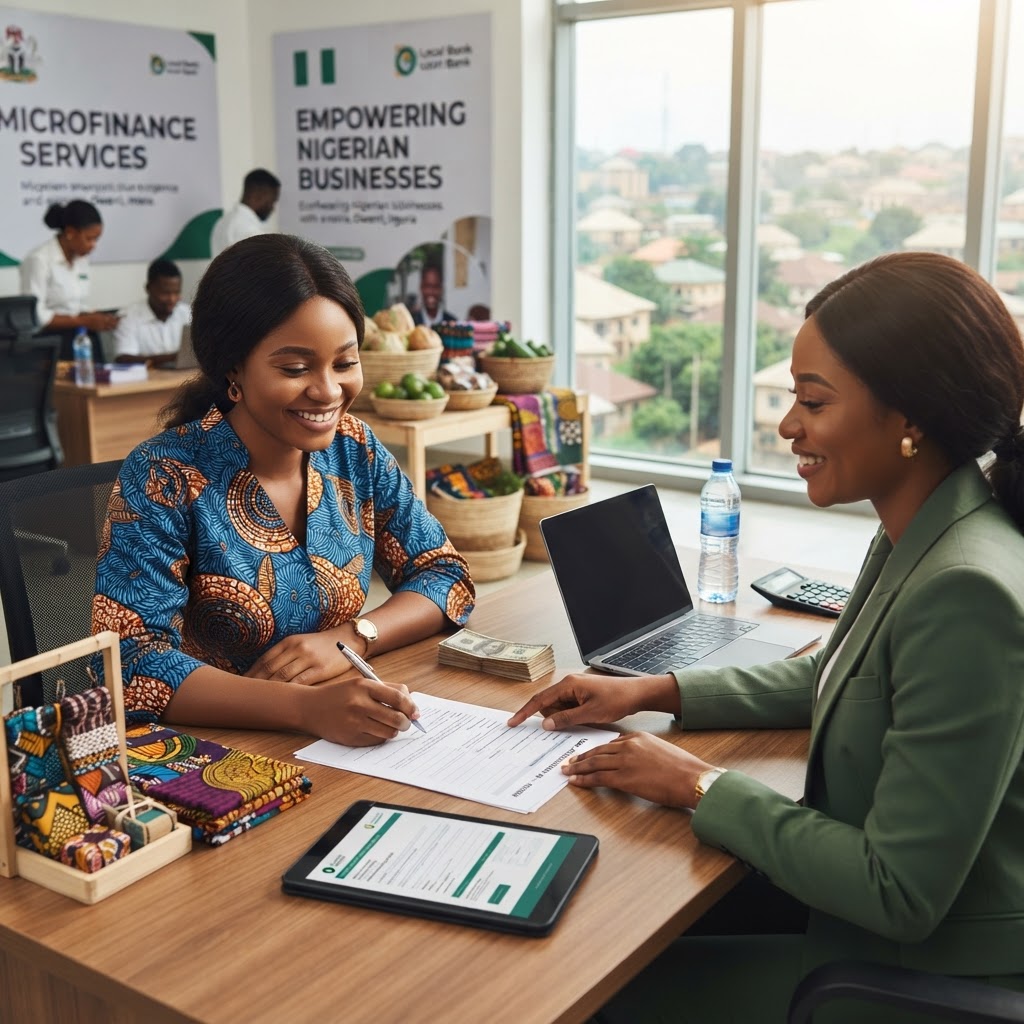
Access to affordable credit remains one of the most significant barriers facing small business owners, farmers, and traders across southeast Nigeria. Whether you operate a provisions stall in Onitsha, run a poultry farm on the outskirts of Enugu, or manage a tailoring workshop in Owerri, understanding how to get microfinance loan in southeast Nigeria can be the difference between stagnation and measurable growth. Microfinance institutions exist precisely to bridge the gap between ambition and capital—but navigating the process requires preparation, documentation, and a clear understanding of how these institutions evaluate risk.
This guide walks you through the mechanics of microfinance credit in Abia, Anambra, Ebonyi, Enugu, and Imo States, covering eligibility, documentation, step-by-step application procedures, realistic cost analysis, and the broader connection between responsible borrowing and community wellbeing.
What Is a Microfinance Loan in Southeast Nigeria?
Grassroots credit across Abia, Anambra, Ebonyi, Enugu, and Imo
Microfinance banks (MFBs) in Nigeria are specialized deposit-taking institutions licensed and regulated by the Central Bank of Nigeria (CBN) to deliver financial services to low-income entrepreneurs, subsistence farmers, and petty traders who fall outside the eligibility criteria of tier-1 commercial banks. These institutions operate under three licensing tiers: Unit MFBs, which serve a single local government area; State MFBs, which operate within a single state; and National MFBs, which function across multiple states.
In southeast Nigeria, microfinance loan products typically include micro-enterprise working capital facilities ranging from ₦50,000 to ₦2,000,000, agricultural cycle financing tailored to cassava and palm oil production timelines, and group solidarity loans that leverage collective social accountability to reduce individual default risk.
A critical distinction worth understanding is the difference between CBN-licensed MFBs and informal rotating savings systems deeply embedded in Igbo culture—known as Isusu or Esusu. While Isusu groups have sustained generations of market women and traders, they offer no formal credit history trail, no regulatory protection, and no mechanism for recovering lost contributions. Transitioning to licensed MFBs formalizes your capital activity, builds a verifiable credit profile with bureaus like CRC Credit Bureau, and ultimately unlocks larger facilities over time.
The regional economic context matters considerably here. Major commercial clusters—Onitsha Main Market and Ariaria International Market in Aba—represent some of the highest-density trading environments in West Africa. Semi-rural agrarian belts in Ebonyi and Enugu, meanwhile, support smallholder farming households who require harvest-cycle financing rather than weekly working capital structures. Understanding which product fits your business model is the foundation of a successful loan application.
Who Qualifies for a Microfinance Loan in the Southeast?
Eligibility, business continuity, and borrower profiles
Not every applicant who walks into a microfinance bank will meet the baseline lending criteria. Most licensed MFBs operating in southeast Nigeria require that a prospective borrower demonstrate a minimum of six months of uninterrupted operation at the same business location. This threshold reflects the lender's need to assess consistent cash flow patterns and reduce the risk of funding volatile or untested ventures.
A foundational prerequisite is maintaining an active savings or current account with the target MFB for at least one to three months prior to application. Credit officers examine account turnover data—daily or weekly deposits reflecting actual trading income—as a proxy for repayment capacity. Sparse or artificially inflated deposits are easily identified and can disqualify an application.
The most commonly funded applicant segments in the southeast include market stallholders managing dry goods, provisions, or electronics; artisan cooperatives of welders, carpenters, and mechanics; private primary school proprietors managing school fees inflows; logistics operators running Keke Napep fleets; and health-focused agricultural processors supplying palm oil, cassava flour, or poultry products to urban markets.
Beyond numerical criteria, local character verification plays a significant underwriting role. Recommendations from recognized market union executives, parish priests, or traditional community rulers—an Igwe or council chairman—carry genuine weight with many community-rooted MFBs. These references serve as qualitative risk indicators, signaling that the borrower is embedded within accountable social structures. This approach mirrors the communal guarantorship model that has underpinned credit in Igbo communities long before formal banking arrived, and it remains a legitimate and practical path for applicants who lack extensive formal documentation. If you are exploring formal cooperative structures to strengthen your community's financial position, the guide on how to form a youth cooperative in Nigeria offers a practical companion framework.
What Documents and Collateral Are Required?
Application dossier, guarantor bonds, and collateral assets
Arriving at a microfinance bank without a complete documentation package is the most common reason applications stall or are rejected outright. A standard application dossier for southeast MFBs must include a completed official loan application form, recent utility bills confirming your residential address, two recent passport photographs, valid government-issued identification (National Identification Number slip, voter's card, or driver's license), and a concise one-page business income and expenditure summary covering the prior three to six months.
Most MFBs in the region require two credible guarantors. Preferred guarantors are civil servants at Grade Level 08 or above, whose stable salaries provide a recovery backstop. Alternatively, verified open-market shop owners with established accounts at the same institution may qualify. Both categories of guarantors must provide notarized letters of undertaking, clearly acknowledging their obligation in the event of borrower default.
Collateral requirements vary significantly with loan size. For facilities under ₦1,000,000, many southeast MFBs accept movable business assets—power generators, grinding machines, sewing equipment, or documented shop inventory liens—in lieu of formal land title documents. Obtaining a Certificate of Occupancy (C of O) is often impractical for applicants in semi-formal commercial zones, and forward-thinking MFBs have adapted their underwriting accordingly.
Two regulatory mechanisms now operate in the background of every formal loan in Nigeria. The Bank Verification Number (BVN) system links your biometric identity to all your bank accounts, enabling credit bureaus and lenders to assess your total liability position instantly. The Global Standing Instruction (GSI) framework, introduced by the CBN in 2020, empowers lenders to recover defaulted loan amounts directly from any of a borrower's accounts at any participating Nigerian bank—including accounts the borrower never disclosed to the lending MFB. Both mechanisms underscore why borrowing responsibly and within your repayment capacity is not merely advisable but financially self-protective.
How Do You Apply for a Microfinance Loan Step-by-Step?
From MFB selection to final disbursement
The application journey, handled methodically, can move from initial inquiry to disbursement within two to four weeks at most structured MFBs.
Step 1: Select a licensed MFB in your locality. Research CBN-licensed institutions operating in your state. Nationally recognized names with southeast presence include LAPO Microfinance Bank, Grooming Centre MFB, and AB Microfinance Bank. Equally important are community-rooted unit MFBs operating within specific LGAs in Enugu, Owerri, Aba, and Awka. You can verify an institution's license status through the CBN's licensed MFB directory. Avoid unlicensed digital loan applications that frequently charge usurious daily rates and deploy aggressive, legally questionable recovery tactics.
Step 2: Initiate relationship banking before you apply. Open an account at your chosen MFB and begin depositing your daily trading proceeds consistently. Request a meeting with an assigned credit officer to discuss your business model, turnover estimates, and intended loan purpose. Building this relationship before formal application signals creditworthiness and gives you insider guidance on how to structure your file.
Step 3: Undergo physical business verification. This is a non-negotiable stage at most reputable MFBs. A credit officer will visit your business premises to inspect shop stock, warehouse inventory, cash receipt books, supplier invoices, and equipment. They will typically interview neighboring stall owners or business partners to corroborate your reported income levels. Transparency at this stage dramatically accelerates approval.
Step 4: Navigate the appraisal and board approval process. Your application is submitted to the credit committee, which reviews CRC Credit Bureau and FirstCentral Credit Bureau reports to check for undisclosed existing loans or prior defaults. A formal offer letter detailing the approved amount, tenor, interest rate, fees, and repayment schedule is generated upon approval. Read this document carefully before signing. Capital is typically disbursed directly into your registered MFB account within 24 to 72 hours of offer acceptance.
What Are the Interest Rates, Fees, and Repayment Terms?
The true cost of borrowing and sustainable repayment
The most important financial literacy exercise any southeast borrower can undertake is calculating the total cost of their loan—not just the headline interest rate. Nigerian microfinance banks typically charge flat monthly interest rates between 3% and 6%, which translate to annualized percentage rates (APR) of 36% to 72%. On a ₦500,000 facility at 4% monthly flat over six months, your total interest charge alone reaches ₦120,000—before fees.
Beyond interest, lenders commonly apply a suite of upfront deductions: loan management fees of 1% to 2% of the principal, administrative processing fees, credit life insurance premiums of 1% to 1.5%, and a compulsory cash collateral or retained equity requirement of 10% to 20% of the loan value. This last item means that on a ₦500,000 loan, you may actually receive ₦400,000 to ₦450,000 in net disbursement while repaying on the full ₦500,000 principal.
Repayment structures vary by business type. Weekly installment models are standard for retail market traders who collect cash daily. Monthly structures are more appropriate for school proprietors collecting termly fees. Agricultural borrowers involved in cassava farming or poultry production often require bullet or harvest-cycle repayment designs, where principal repayment aligns with seasonal income. Negotiate the structure that matches your cash flow cycle rather than accepting the default template.
The most effective safeguard against default is operational: maintain a strict separation between business working capital and household expenditure. Mixing funds is one of the leading behavioral causes of SME loan default in Nigeria. Financial stress from unserviced debt has documented psychological consequences—for a deeper look at managing mental health within financially constrained environments, the resource on mental health support for Nigerians in rural areas offers grounded, practical guidance.
How Does Responsible Borrowing Build Community Wealth?
Financial liquidity, family welfare, and collective prosperity
The decision to borrow responsibly is not merely a personal financial calculation—it is a community development act. Research consistently links chronic debt distress to elevated cortisol levels, hypertension, and anxiety disorders. In contrast, disciplined capital deployment—borrowing purposefully, deploying productively, and repaying consistently—builds economic stability that generates measurable improvements in family wellbeing, including better nutrition, more reliable healthcare access, and stronger educational investment for children.
Across southeast Nigeria, thriving micro-enterprises fund far more than their owners' incomes. A successful market trader who grows her working capital from ₦200,000 to ₦1,000,000 over three loan cycles does not just increase her profit margin—she funds school fees, sponsors apprentices through the Igba Boyi vocational training tradition, employs local youth as assistants, and contributes to community levies that maintain roads and market infrastructure. Individual business growth aggregates into grassroots development.
The principle of debt hygiene deserves emphasis: avoid simultaneously borrowing from multiple MFBs, a practice that inflates your CBN credit bureau debt-to-income ratio and increases default probability exponentially. Reinvest loan-funded profits into tangible business assets before expanding your credit appetite. The long-term objective should be gradual transition from debt dependence toward retained capital sovereignty—building a business that funds its own growth cycle rather than perpetually relying on external credit.
Sound public financial accountability supports the broader environment in which these micro-economies thrive. Understanding how community funds flow—or fail to—is relevant context, as explored in reporting on Mbaitoli LGA's ₦6.2 billion FAAC allocation and the accountability questions surrounding Imo State's ₦350 million NBA controversy.
Conclusion
Learning how to get microfinance loan in southeast Nigeria requires more than knowing where to apply—it demands deliberate preparation, financial self-awareness, and strategic relationship-building with licensed institutions. From understanding CBN-tier classifications and assembling a solid documentation dossier, to calculating the true annualized cost of credit and structuring repayments around your actual cash flow, every step in the process rewards informed applicants.
The microfinance sector, when engaged responsibly, is one of the most powerful grassroots wealth-creation tools available to southeast Nigerian entrepreneurs. It is also, when misused, a source of financial stress that ripples outward into household health and community stability. Approach your first—or next—microfinance loan with the clarity and discipline this guide has outlined, and you position yourself not merely as a borrower, but as a builder of durable, community-anchored prosperity.
For further guidance on the regulatory environment governing Nigerian financial institutions, consult the CBN Microfinance Policy Framework and the NDIC's deposit insurance resources for MFB depositor protection information.
Stay Informed
Get New Articles in Your Inbox
Subscribe to receive the latest community development, health, and wealth insights from Eziokwubundu.
Newsletter
Practical insights on health, wealth, and community — delivered weekly.