Powered by Obi Mbieri Independent Media Ltd · eziokwubundu.com
$1 = ₦1,326€1 = ₦1,541£1 = ₦1,793How to form a youth cooperative in Nigeria
Starting a cooperative is one of the most powerful economic decisions a group of young Nigerians can make together. In a country where commercial bank loans carry interest rates exceeding 20%, where unemployment among youth hovers around 33%, and where individual small businesses face systemic barri...
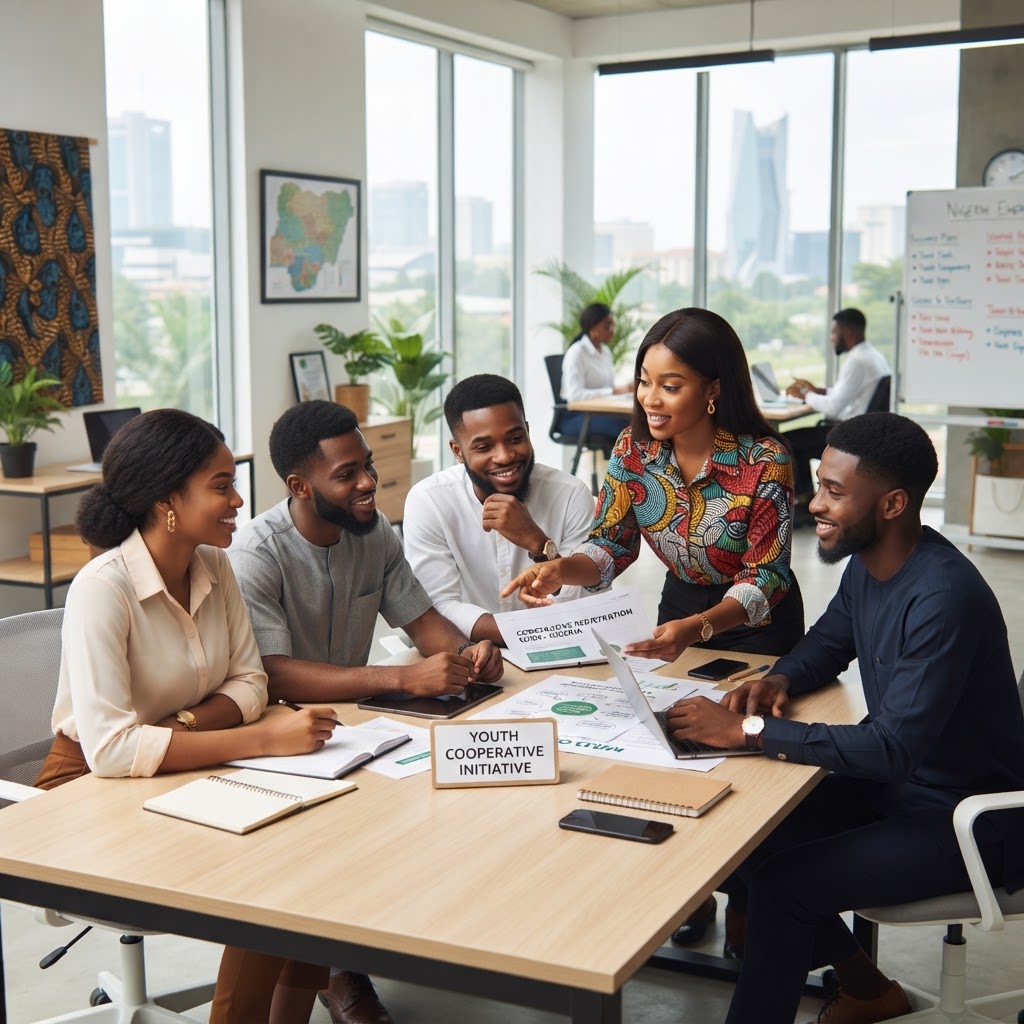
Starting a cooperative is one of the most powerful economic decisions a group of young Nigerians can make together. In a country where commercial bank loans carry interest rates exceeding 20%, where unemployment among youth hovers around 33%, and where individual small businesses face systemic barriers to growth, the cooperative model offers a structured, legally recognized, and community-rooted alternative. This guide walks you through every essential step — from understanding the legal framework to registering your group and building long-term sustainability.
Whether you are a fresh graduate in Lagos, a young entrepreneur in Enugu, or a community leader in Imo State, this article provides the actionable knowledge you need to transform collective ambition into a functioning cooperative enterprise.
What is a youth cooperative in Nigeria?
Legal roots and community identity
A cooperative society in Nigeria is a voluntary association of individuals who come together to meet shared economic, social, and cultural needs through a jointly owned and democratically controlled enterprise. The governing legal framework is the Nigerian Cooperative Societies Act (Cap C35, Laws of the Federation 2004), which is complemented by state-level cooperative laws administered through each state's Ministry of Commerce or Department of Cooperative Services.
A foundational principle of any valid cooperative is the Common Bond — the requirement that all members share a unifying characteristic, whether that is a residential area, occupation, or social interest. This shared identity creates the mutual accountability that makes cooperative finance and governance function effectively without the bureaucratic overhead of a commercial institution.
Unlike a Limited Liability Company (LLC), which is designed to generate returns for external shareholders, a cooperative is structured to serve its members. Profit distribution, called a surplus, is shared based on member participation rather than capital contribution. Governance follows the one-member, one-vote rule — a direct expression of democratic equity.
From a cultural standpoint, cooperatives are not foreign imports. They are modern legal extensions of traditional Nigerian saving structures like Ajo (common in Yoruba communities) and Esusu (widespread across Igbo communities). These time-tested institutions encoded trust, reciprocity, and collective discipline long before formal legislation existed. A youth cooperative formalizes that same ethos within the modern economy.
Why cooperatives beat standard business for Nigerian youth
Credit, community, and collective resilience
Data from Nigeria's cooperative sector consistently shows that organized cooperative members enjoy significantly better access to credit than their peers who operate as sole traders. Research indicates that 51.1% of cooperative members gain easier access to credit compared to individual entrepreneurs who must confront commercial banks charging prime lending rates that have ranged from 18% to 27% in recent years.
The One Kindred, One Business Initiative (OKOBI) offers a compelling model here. By anchoring enterprise to community identity, OKOBI reduces individual financial exposure through collective resource pooling — precisely the logic that makes cooperatives viable where individual startups fail. When ten young people pool their resources toward a shared goal, the risk per person diminishes while the collective purchasing power multiplies.
Cooperatives also serve a critical social function: they combat brain drain. When local leadership opportunities exist and profits are reinvested within the community, ambitious young people have tangible reasons to remain and build rather than relocate abroad or to major cities. This stabilizes local economies and builds the social infrastructure necessary for generational wealth.
The Health + Wealth synergy within cooperatives deserves specific attention. A well-structured cooperative can maintain an emergency welfare fund that covers sudden medical costs for members. This matters enormously in Nigeria, where out-of-pocket healthcare expenditure regularly pushes small business owners below the financial stability threshold. For more on savings strategies that support this kind of financial resilience, see our guide on the best savings plans for low income Nigerians.
What types of cooperative can you form?
Matching structure to your group's purpose
Nigeria's cooperative landscape offers several structural models, and selecting the right one determines your group's operational focus and legal requirements.
Thrift and Credit Cooperative Societies (TCCS) are among the most common. Members make regular monthly savings contributions into a collective fund, which then circulates as low-interest loans for education fees, business capital, or emergency needs. The interest charged is typically between 5% and 10% — far below commercial bank rates.
Multipurpose Cooperatives represent the dominant model in urban Nigerian environments. They combine savings and credit functions with consumer goods distribution and joint investment activities, allowing members to meet a wider range of economic needs through a single institutional structure.
Specialized Cooperatives focus on a specific sector. Agricultural and agribusiness cooperatives are particularly impactful in Nigeria's productive south and middle belt regions. In Oyo State, for instance, cooperative group assets account for approximately 34% of total member benefits, demonstrating how collective farming and produce marketing amplify individual farmer outcomes.
Consumer Cooperatives are increasingly relevant in an inflationary environment. By purchasing essential commodities — food, stationery, household goods — in bulk at wholesale prices and distributing them to members at cost, these cooperatives function as practical shields against Nigeria's persistent inflation cycles.
What are the requirements to get started?
Membership thresholds and essential documentation
Before your group can apply for registration, several baseline conditions must be satisfied. Most state-level cooperative regulations require a minimum of 10 to 20 founding members, though the exact figure varies by state and cooperative type. Your state's Ministry of Commerce and Industry or its Department of Cooperative Services is the authoritative source for the applicable threshold.
The regulatory process typically requires the submission of a feasibility study or economic survey. This document demonstrates to the Director of Cooperatives that your proposed cooperative has a viable economic purpose, a realistic member base, and a credible plan for financial sustainability. It is not a formality — regulators use it to screen out unstable formations.
On the financial side, your founding members must agree on and document three key figures: the entrance fee (a one-time payment upon joining), the minimum monthly savings contribution each member will make, and the value of individual share capital (the portion of ownership each member holds). These figures must be realistic, equitable, and clearly stated in your by-laws.
Essential documents for the first stage include a formal letter of intent addressed to the state Director of Cooperatives, as well as a proposed cooperative name submitted for an availability search. Additional records such as a member register, draft by-laws, and minutes of your preliminary meetings will be required in subsequent stages.
How do you navigate the registration process?
From inaugural meeting to official certificate
The official registration process begins with the inaugural meeting — a formally convened and documented assembly of all founding members. This meeting must produce signed minutes that record attendance, the proposed cooperative name, the agreed objectives, the elected executive management committee (typically a chairperson, secretary, and treasurer), and the initial financial parameters. These minutes carry legal weight throughout the registration process.
Following the inaugural meeting, the group must draft its By-laws — the governing constitution of the cooperative. By-laws must be consistent with the Nigerian Cooperative Societies Act and must address critical provisions including membership eligibility and withdrawal procedures, share capital and savings obligations, surplus distribution formulas, conduct of annual general meetings, and internal dispute resolution mechanisms. Many state-level cooperative offices provide template by-laws that can be adapted to your specific cooperative type.
Featured Products
Chukwu Abiama Tee
Bold black-and-gold Igbo-pride T-shirt featuring 'Chukwu Abiama' in premium streetwear typography.
₦15,000
Buy NowReverse Type 2 Diabetes & other associated Metabolic Issues using Dr. Jason Fung's Evidence-Based Approach— FMD program for Type 2 Diabetes
A practical fasting and fasting-mimicking programme built on Dr Jason Fung's insulin-resistance principles and ow-glycemic recipes.
₦19,950
Join NowỤmụ Igbo Tee
Classic black T-shirt with bold white 'Ụmụ Igbo' typography — a proud statement of Igbo heritage.
₦15,000
Buy NowNwanne Tee
Washed khaki vintage tee with a faded rust-orange 'Nwanne' stamp badge and palm leaf motif — a nod to kinship and heritage.
₦18,000
Buy NowObodo Tee
Faded denim-blue washed tee with a cream 'Obodo' stamp badge and sun motif, celebrating community roots.
₦18,000
Buy NowEkwe Heritage Tee
Deep indigo tee featuring a fine line-art illustration of a traditional Igbo ekwe drum, inspired by Igbo-Ukwu bronze artistry.
₦18,000
Buy NowIkenga Figure Tee
Forest green tee with a fine line-art illustration of a stylized Ikenga figure.
₦18,000
Buy NowOnce your by-laws are finalized, you submit the complete application package — including the letter of intent, member register, economic survey, inaugural meeting minutes, and by-laws — to the State Director of Cooperatives. Registration fees typically range from ₦10,000 to ₦20,000, depending on the state and cooperative category. The processing period is generally two to three months, during which the cooperative office may schedule an inspection or request clarification on submitted documents.
Upon successful review, your group receives a Certificate of Registration. This is not a ceremonial document. It is a legal instrument that grants the cooperative its own independent legal identity — enabling it to open a dedicated corporate bank account, enter into contracts, acquire property, and sue or be sued in its own name. Without this certificate, your cooperative operates in a legal grey area that exposes members to personal financial liability.
Understanding how community institutions exercise formal authority is relevant background here. Our article on community leadership in Imo — village head, town union, or traditional ruler offers useful context on how different structures share governance at the grassroots level.
For authoritative registration guidance, visit the Federal Department of Cooperatives under Nigeria's Federal Ministry of Agriculture or consult your specific state's cooperative services office directly.
How can cooperatives improve member health and wellness?
Connecting economic security to physical wellbeing
A cooperative that only focuses on financial returns misses a critical dimension of community development. The Community-First Approach to health recognizes that economic insecurity is itself a health risk — and that collectively organized groups are uniquely positioned to address it.
One of the most impactful health benefits cooperatives can deliver is access to group health insurance. By negotiating with HMOs (Health Maintenance Organizations) registered under Nigeria's National Health Insurance Authority (NHIA), cooperatives can secure group health plans at premiums 30% to 50% lower than individual policies. For young Nigerians who rarely qualify for employer-sponsored healthcare, this is transformative.
Beyond insurance, cooperatives can fund wellness education programs as a formal part of their social responsibility budget. Workshops on managing blood sugar through culturally relevant Nigerian diets, sessions on maternal nutrition, and training on preventive healthcare practices are all achievable at low cost when organized collectively. See our detailed resource on nutrition tips for pregnant women in Nigeria as an example of the kind of evidence-based guidance cooperatives can incorporate into member wellness programs.
The psychological dimension is equally significant. Entrepreneurship in Nigeria is a high-stress undertaking, marked by infrastructure deficits, regulatory unpredictability, and financial uncertainty. The cooperative structure provides a social support network that reduces isolation and shares the cognitive burden of decision-making. Studies in community economics consistently link cooperative membership to lower reported anxiety levels among small business operators.
Several productive cooperatives have taken this further by establishing emergency health funds — a dedicated pool of money set aside exclusively for medical crises. When a member faces a sudden hospitalization, this fund prevents the forced closure of their business, the liquidation of savings, or descent into debt bondage to informal lenders.
For broader reading on evidence-based health financing in Nigeria, the World Health Organization's Nigeria country health profile provides relevant data on out-of-pocket expenditure and healthcare access gaps.
What ensures a cooperative's long-term survival?
Governance, technology, and inter-cooperative networks
The most common cause of cooperative failure in Nigeria is not external competition — it is internal mismanagement. Avoiding this requires deliberate structural safeguards from the founding stage onward.
Generative Leadership — a governance philosophy focused on building assets for the next generation rather than extracting value for the present — should be embedded in your cooperative's culture and by-laws. Leadership transitions must be routine, transparent, and governed by term limits. A cooperative that becomes dependent on a single personality is a cooperative at risk.
Financial transparency is the second pillar of sustainability. The integration of fintech tools and cooperative management software — platforms such as CoopCentral, eTranzact cooperative modules, or even structured use of shared spreadsheet systems with audit trails — enables members to track contributions, loans, and repayments in real time. This dramatically reduces the embezzlement risk that has destroyed numerous promising cooperative societies in Nigeria.
Regular auditing by the State Department of Cooperative Services is not optional — it is a legal requirement under the Cooperative Societies Act. Proactive compliance with audit schedules signals institutional integrity and builds member confidence. Groups that resist auditing signal fragility.
Finally, the Cooperation among Cooperatives principle — the seventh principle of the International Cooperative Alliance — encourages local societies to affiliate with state and national apex cooperative bodies. In Nigeria, apex organizations such as the Nigerian Cooperative Federation (NCF) provide political advocacy, bulk procurement advantages, and training resources that individual cooperatives cannot access alone. Joining these networks multiplies leverage.
For context on how collective community institutions fight for accountability and representation in Nigeria, our coverage of why villages and autonomous communities must demand accountability offers directly relevant parallels.
Useful external resources include the International Cooperative Alliance's cooperative principles and the Nigerian Cooperative Federation's official platform for apex-level affiliation and training support.
Conclusion
Forming a youth cooperative in Nigeria is a structured, achievable, and potentially transformative process. It demands seriousness — proper documentation, legal compliance, transparent governance, and a shared commitment to collective wellbeing — but the rewards extend far beyond any single member's individual gain.
A well-formed cooperative creates credit access where banks refuse to lend, builds health security where insurance is unaffordable, and generates community leadership where brain drain threatens to hollow out local capacity. It blends the ancient Nigerian wisdom of Esusu with modern legal and financial tools to create something genuinely powerful: a community-owned engine for practical prosperity.
Start with the right people, define your common bond, follow the registration process with discipline, and invest in transparent governance from day one. The cooperative you build today can serve your community's children tomorrow.
Stay Informed
Get New Articles in Your Inbox
Subscribe to receive the latest community development, health, and wealth insights from Eziokwubundu.
Newsletter
Practical insights on health, wealth, and community — delivered weekly.