Powered by Obi Mbieri Independent Media Ltd · eziokwubundu.com
$1 = ₦1,327€1 = ₦1,540£1 = ₦1,795Best savings plans for low income Nigerians
Building financial security on a tight budget in Nigeria is not a theoretical exercise — it is a daily act of discipline, strategy, and resistance against a challenging economic environment. With inflation eroding purchasing power and the naira under persistent pressure, low-income earners face a sy...
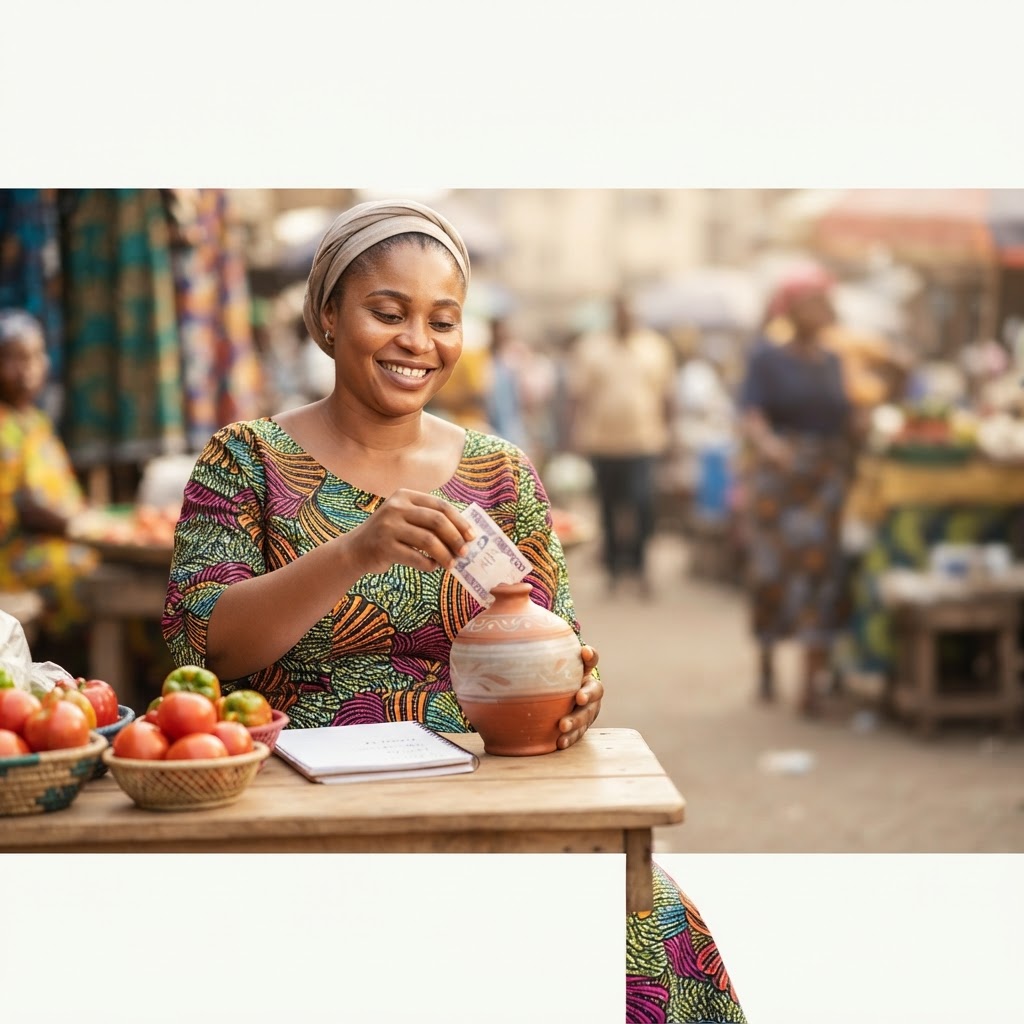
Building financial security on a tight budget in Nigeria is not a theoretical exercise — it is a daily act of discipline, strategy, and resistance against a challenging economic environment. With inflation eroding purchasing power and the naira under persistent pressure, low-income earners face a system that seems designed to keep them from getting ahead. Yet thousands of Nigerians are quietly and consistently building savings using tools that were unavailable even five years ago.
This guide provides a practical, Africa-centred breakdown of the best savings plans for low income Nigerians — from high-yield fintech apps and insurance-linked savings products to community cooperatives and USSD-based microfinance. Whether you earn a daily wage, run a petty trade, or are a student trying to build financial discipline, there is a strategy here that fits your reality.
Why Is Saving So Hard for Low-Income Nigerians?
Understanding the systemic and cultural barriers to wealth accumulation is the first step toward overcoming them. According to the National Bureau of Statistics, approximately 63% of Nigerians live in multidimensional poverty — meaning that even where some income exists, it is stretched across layers of deprivation that include inadequate healthcare, poor housing, and unreliable energy. In this context, the standard financial advice to "save 20% of your income" is not just unrealistic; it is disconnected from lived Nigerian experience.
Inflation compounds the problem. Nigeria's headline inflation rate climbed above 30% in 2024, meaning that money sitting idle in a zero-interest account is actively losing value every month. The Central Bank of Nigeria's own monetary policy decisions have prioritised exchange rate management, but the downstream effects on everyday earners remain brutal.
Beyond macroeconomics, cultural obligations impose what is widely called the "Black Tax" — the financial burden carried by working Nigerians who are expected to support extended family members, fund community events, pay for funerals, and contribute to neighbourhood levies. These are not optional expenses in many communities; they are social contracts. For low-wage earners, this leaves virtually nothing to commit to long-term financial goals before the month ends.
At eziokwubundu.com, the "Practical Prosperity" framework acknowledges this reality without dismissing it. The shift from abstract saving goals to micro-saving — saving ₦200 today, ₦500 tomorrow, deliberately and consistently — reframes the act of saving as economic resistance, not delayed gratification. Small amounts, saved with intention, compound into something real.
Which Digital Apps Offer the Best Returns for Small Deposits?
The emergence of Nigerian fintech has created a genuinely powerful toolkit for the small-scale saver. These platforms were designed with accessibility in mind, and several offer interest rates that traditional commercial banks simply cannot match.
Moniepoint has expanded beyond agency banking into personal savings products, offering up to 17.5% per annum on fixed deposit savings. For a low-income earner depositing ₦20,000 monthly, this represents a meaningful annual return that partially offsets inflation drag.
Renmoney takes a more aggressive approach, offering savings interest rates that can reach up to 28% per annum for funds locked in fixed tenures. This makes it one of the strongest inflation hedges currently available to everyday Nigerians in the digital space.
PiggyVest's Target Savings feature allows users to create a dedicated savings goal — for school fees, a generator, or a business investment — and lock funds until a target date is reached. You can start with as little as ₦100, which makes this platform genuinely accessible to students and petty traders. PiggyVest is regulated and maintains partnerships with licensed financial institutions in Nigeria.
Cowrywise takes an automated approach, with triggers that allow you to set savings rules — for example, saving ₦500 every time you receive airtime recharge. Its mutual fund options also give low-income earners access to investment vehicles previously reserved for wealthier individuals.
Security and trust are valid concerns. Both PiggyVest and Cowrywise operate under regulatory oversight from the Securities and Exchange Commission (SEC) and maintain arrangements with NDIC-insured banks. This is a critical factor for community members who remain cautious about digital platforms after high-profile fintech failures elsewhere on the continent. These are not informal schemes; they are regulated financial products.
How Can You Save for Health and Wealth Simultaneously?
One of the most underappreciated risks to financial stability in Nigeria is a medical emergency. A single hospitalisation can wipe out months of careful savings — and for low-income families, it can mean selling assets, taking predatory loans, or withdrawing children from school. This is where the integrated "Health + Wealth" model becomes transformative.
ALLYCare is one of the most innovative products in this space, offering savings accounts that generate up to 20% annual returns while bundling free or heavily subsidised health insurance coverage into the plan. This means that every naira saved is simultaneously building a financial reserve and providing protection against the health shocks most likely to deplete it. For Nigerian families who cannot afford to separate health costs from household expenses, this integration is not a luxury — it is a necessity.
The Leadway Smart Cash Plan, offered by Leadway Assurance, is an insurance-linked savings product that provides life coverage while accumulating a cash value over time. For families, this is a safety net that ensures a medical or life emergency does not translate into total financial collapse. Plans can be structured with modest monthly premiums, making them accessible across income levels.
At eziokwubundu.com, we call this approach "Preventive Healthcare as Wealth Preservation." The logic is straightforward: a family that maintains basic health coverage, eats thoughtfully, and avoids catastrophic out-of-pocket medical costs preserves more wealth over a five-year period than a family that earns more but has no health safety net. You can explore this concept further in our article on how to treat malaria with local Nigerian herbs, which illustrates how accessible health knowledge reduces avoidable costs.
This dual approach — growing money while protecting health — is precisely what the Health + Wealth + Community philosophy at eziokwubundu.com was designed to enable.
What Options Exist for Nigerians Without Smartphones?
Digital savings apps are powerful, but they remain inaccessible to a significant portion of Nigeria's population. An estimated 60% of Nigerians do not have smartphones, and many rural and semi-urban communities have limited internet access. For these earners, the best savings plans look different — but they are no less effective.
Microfinance Banks (MFBs) are the backbone of grassroots financial access in Nigeria. Institutions like Magajin-Gari Microfinance Bank in northern Nigeria, along with dozens of state-licensed MFBs across the south, offer savings products accessible through USSD codes — short numeric codes like *901# that work on any basic mobile phone without internet. You can check your balance, deposit, and even transfer funds using a ₦3,000 Nokia phone.
Agency banking hubs, operated by licensed agents in local government areas, extend the footprint of formal banking to market stalls, motor parks, and village squares. Through platforms like OPay and Firstmonie Agents, you can open a savings account and make deposits within walking distance of your home.
Featured Products
Chukwu Abiama Tee
Bold black-and-gold Igbo-pride T-shirt featuring 'Chukwu Abiama' in premium streetwear typography.
₦15,000
Buy NowReverse Type 2 Diabetes & other associated Metabolic Issues using Dr. Jason Fung's Evidence-Based Approach— FMD program for Type 2 Diabetes
A practical fasting and fasting-mimicking programme built on Dr Jason Fung's insulin-resistance principles and ow-glycemic recipes.
₦19,950
Join NowỤmụ Igbo Tee
Classic black T-shirt with bold white 'Ụmụ Igbo' typography — a proud statement of Igbo heritage.
₦15,000
Buy NowNwanne Tee
Washed khaki vintage tee with a faded rust-orange 'Nwanne' stamp badge and palm leaf motif — a nod to kinship and heritage.
₦18,000
Buy NowObodo Tee
Faded denim-blue washed tee with a cream 'Obodo' stamp badge and sun motif, celebrating community roots.
₦18,000
Buy NowEkwe Heritage Tee
Deep indigo tee featuring a fine line-art illustration of a traditional Igbo ekwe drum, inspired by Igbo-Ukwu bronze artistry.
₦18,000
Buy NowIkenga Figure Tee
Forest green tee with a fine line-art illustration of a stylized Ikenga figure.
₦18,000
Buy NowTo open a Tier-1 savings account at most MFBs, you need only two things: your BVN (Bank Verification Number) and an active phone number. There is no minimum balance requirement, no passbook fee at most branches, and no requirement for utility bills or employment letters. Visit your nearest MFB branch, present your phone number linked to your BVN, and you can be saving formally within the hour.
Do Dollar Savings Protect Nigerians from Naira Devaluation?
For low-income earners thinking beyond month-to-month survival, dollar-denominated savings offer a powerful hedge against naira volatility. The naira lost over 40% of its value against the US dollar in a single year — meaning that any naira-only savings strategy carries an embedded currency risk that can quietly destroy years of effort.
PiggyVest's Flex Dollar wallet allows Nigerians to save in US dollars starting from as little as $1, earning approximately 6% interest per annum. The dual benefit is clear: you earn interest in dollars while also benefiting from any naira-to-dollar exchange rate movement. When the naira weakens further, your dollar balance is worth proportionally more in local currency terms.
The Pesa platform operates similarly, targeting African savers with micro-dollar deposit options and competitive interest rates, with liquidity options that suit savers who may need periodic access to funds.
The alternative — a domiciliary account at a commercial bank — offers dollar security but often lacks the liquidity and accessibility features of fintech wallets. Minimum deposit requirements and limited branch access make domiciliary accounts less practical for low-income earners.
The Practical Prosperity recommendation here is specific: use dollar savings exclusively for long-term goals with a timeline of two years or more. School fees for children, the purchase of imported tools for a small business, or building a foreign currency emergency fund are ideal targets. This preserves the exchange rate benefit while preventing impulsive withdrawals.
Can Community Cooperatives Beat Modern Banks?
Long before fintech apps existed, Nigerians had already built one of the world's most effective informal savings systems. The Ajo (Yoruba) and Esusu (Igbo) cooperative models — rotating savings groups where members contribute fixed amounts weekly or monthly and take turns receiving the total pot — remain remarkably effective, particularly when formalised through registered cooperatives.
Modern registered cooperatives go further. They offer interest-free loans to members, collective investment in community assets, and a level of social accountability that no algorithm can replicate. When your neighbour is the loan officer and your market association is the board, the incentive to honour commitments is deeply personal.
As we explore in our coverage of community leadership in Imo: village head, town union or traditional ruler — who does what?, community structures in Nigeria hold real economic power when properly organised. This intersects directly with the eziokwubundu "Traditional Values, Modern Progress" content angle — the idea that indigenous financial wisdom, updated with modern governance and record-keeping, can outperform conventional banking for grassroots earners.
For accountability-driven personalities, community cooperatives win on social enforcement. For disciplined self-starters who prefer privacy, fintech apps offer automated structure without social pressure. The most effective savers often use both: a cooperative for community lending and social capital, and a digital app for private wealth accumulation.
How Do You Build an Emergency Fund on a Low Income?
The standard 50/30/20 budgeting rule — 50% on needs, 30% on wants, 20% on savings — assumes a level of income surplus that most low-income Nigerians simply do not have. A more realistic framework is the 70/20/10 split: 70% on essential needs, 20% on financial obligations and debt reduction, and a strict 10% on emergency savings, kept in a separate account with no debit card attached.
The key is separation. When your emergency fund lives in the same account as your daily spending money, it is not an emergency fund — it is a delayed expense. Platforms like PiggyVest's SafeLock or a dedicated MFB savings account without mobile app access create the friction needed to leave that money untouched.
Beyond direct savings, bulk buying is an underutilised wealth-building tool. Families that pool resources through community clusters to purchase non-perishable food items — rice, beans, garri, groundnut oil — in bulk can reduce monthly food expenses by up to 15%. That percentage, redirected to savings, adds up to meaningful amounts over twelve months.
The most important mindset shift is this: saving ₦1,000 every week is worth more than waiting for a large lump sum that may never arrive. At that rate, you accumulate ₦52,000 in a year — enough to cover a moderate medical emergency, pay a school fee instalment, or start a small trade. As we noted in our analysis of the ₦300,000 minimum wage demand and what Nigerian workers are asking Tinubu to do, the fight for better wages matters — but financial strategy must function in the present economy, not the ideal one.
The Bottom Line on Saving on a Low Income
The best savings plans for low income Nigerians are not found in a single app or product. They are found in a deliberate combination of tools: a high-yield fintech account for digital earners, a USSD-accessible microfinance account for those without smartphones, an insurance-linked savings plan that doubles as health protection, a dollar wallet for long-term currency hedging, and a community cooperative for social capital and interest-free credit.
The eziokwubundu framework — Health + Wealth + Community — reflects a truth that mainstream financial advice rarely acknowledges: for Nigerians, individual financial security is inseparable from community health and collective progress. When your neighbours are financially stable, your street is safer. When your community saves together, it builds together.
Start with ₦100 today. Open one account this week. Join or form one savings group this month. These are not small steps — they are the foundation of lasting prosperity.
For further reading on community accountability structures that support collective financial growth, explore our piece on community leadership in Imo: why villages and autonomous communities must demand accountability.
Sources and further reading: National Bureau of Statistics Nigeria | Central Bank of Nigeria | PiggyVest Platform Overview | Cowrywise Help Centre
Stay Informed
Get New Articles in Your Inbox
Subscribe to receive the latest community development, health, and wealth insights from Eziokwubundu.
Newsletter
Practical insights on health, wealth, and community — delivered weekly.